
By Jeremy
Published August 10, 2026
Your effective rate is your total monthly processing fees divided by your total monthly card volume, expressed as a percentage. A headline rate is a single quoted number that covers only part of your bill. Effective rate is the only figure that lets you compare two processors honestly, because it counts every fee.
The formula is short enough to run on a phone:
Effective rate = (Total fees / Total volume) x 100
Everything else on this page exists to show you where the gap between those two numbers comes from, and how to prove it on your own statement in about fifteen minutes.
The Three Numbers That Describe Your Real Cost
One number is not enough. Two merchants can post the same effective rate and have completely different problems, so calculate all three every time.
| Metric | Formula | What it tells you | What moves it |
|---|---|---|---|
| Effective rate | (Total fees / Total volume) x 100 | Your all-in cost as a percentage of every dollar you run | Card mix, markup, downgrades, fixed fees, volume swings |
| Cost per transaction | Total fees / Transaction count | What each sale costs you to accept, in dollars | Average ticket, per-item fees, batch and dispute activity |
| Average ticket | Total volume / Transaction count | The size of a typical sale, which drives both numbers above | Product mix, promotions, seasonality, minimum purchase rules |
The 4-Phase Effective Rate Calculation
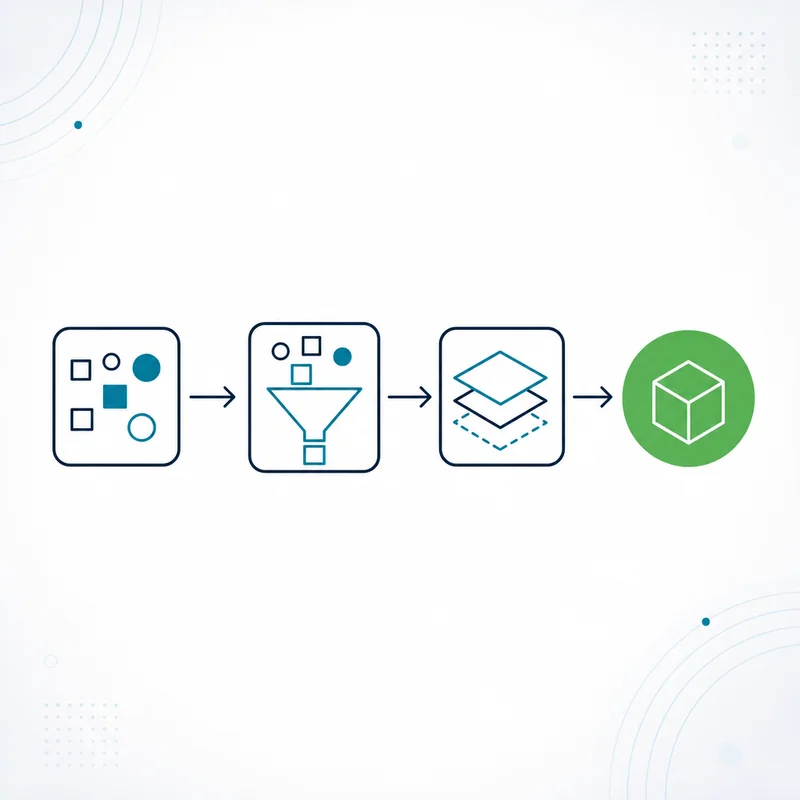
You do not need to understand interchange to run this. You need one full statement, a calculator, and about fifteen minutes.
Phase 1: Gather the three inputs from one full statement
- Total card volume: Use the total dollar amount of card sales the processor settled for the month, sometimes labeled gross sales, total submitted, or amount submitted.
- Total fees: Use every dollar the processor took for the month, including amounts netted out of daily deposits and amounts debited separately from your bank account.
- Transaction count: Use the total number of settled sales for the month, not the number of batches and not the number of customers.
- One full statement: Pull the complete multi-page statement rather than a portal summary screen, because summary views frequently omit the fixed monthly items.
Phase 2: Run the three calculations
- Effective rate: Divide total fees by total volume, then multiply by 100 to express the result as a percentage.
- Cost per transaction: Divide total fees by transaction count to get the dollar cost of accepting one typical sale.
- Average ticket: Divide total volume by transaction count, because average ticket explains most of the difference between the first two numbers.
- Full precision first: Do the division before you round anything, since rounding each fee line first can shift the result by several basis points.
Phase 3: Compare the result against the rate you were quoted
- Restate the quote exactly: Write down the quoted percentage and any quoted per-transaction amount, along with anything the quote explicitly excluded.
- Predict the bill from the quote: Multiply your volume by the quoted percentage, add the quoted per-transaction amount times your transaction count, and treat that total as the prediction.
- Measure the gap: Subtract the predicted total from what you actually paid, and convert that difference into percentage points of your volume so it is comparable to the quote.
- Do not skip a small gap: A gap of a quarter of one percent on modest volume is still real money over a year, and it usually points at a fee category you did not know existed.
Phase 4: Explain the gap line by line
- Separate pass-through from markup: Interchange and card-brand assessments are set by the card networks and reach every merchant, while the markup is the part your agreement actually sets.
- Isolate the fixed monthly fees: Add up every item that would bill the same in a slow month, then divide that subtotal by your volume to see the percentage it contributes.
- Check where your volume qualified: On tiered pricing, look at how much volume landed in the non-qualified bucket, because that is where a low advertised rate quietly stops applying.
- Repeat for three months: Run the same calculation on three statements in a row, since a single month can be distorted by a dispute, an annual fee, or a seasonal swing.
Worked Example: A Statement That Reconciles Exactly
Every number below is illustrative. These are made-up figures used to demonstrate the arithmetic. They are not PayPoint Systems rates, not a quote, not a benchmark, and not a representation of what any merchant pays.
The setup. An illustrative retail merchant was quoted a headline rate of 1.99 percent by an inbound sales call. The quote mentioned no per-transaction fee and no monthly fees. Here is what the month actually looked like.
| Input | Value |
|---|---|
| Total card volume settled | $50,000.00 |
| Total transactions settled | 1,250 |
| Batches settled | 25 |
| Disputes received | 1 |
| Headline rate quoted | 1.99% (no per-transaction or monthly fees mentioned) |
Every fee on the statement. This is the full fee stack. Nothing is omitted, and the column of percentages adds to the effective rate exactly.
| Fee line | How it is calculated | Amount | Percent of volume |
|---|---|---|---|
| Interchange (pass-through to the card brands) | 1.80% of $50,000.00 | $900.00 | 1.80% |
| Card-brand assessments and network fees | 0.14% of $50,000.00 | $70.00 | 0.14% |
| Provider percentage markup | 0.45% of $50,000.00 | $225.00 | 0.45% |
| Provider per-transaction markup | 1,250 transactions x $0.12 | $150.00 | 0.30% |
| Monthly service and statement fee | Fixed, billed once | $15.00 | 0.03% |
| Gateway and virtual terminal fee | Fixed, billed once | $30.00 | 0.06% |
| PCI program fee | Fixed, billed once | $20.00 | 0.04% |
| Wireless data plan fee | Fixed, billed once | $10.00 | 0.02% |
| Batch settlement fees | 25 batches x $0.20 | $5.00 | 0.01% |
| Dispute or chargeback fee | 1 dispute x $25.00 | $25.00 | 0.05% |
| Total fees | Sum of all lines above | $1,450.00 | 2.90% |
The three outputs. Each division below terminates exactly, with no rounding applied.
| Output | Arithmetic | Result |
|---|---|---|
| Effective rate | ($1,450.00 / $50,000.00) x 100 | 2.90% |
| Cost per transaction | $1,450.00 / 1,250 | $1.16 |
| Average ticket | $50,000.00 / 1,250 | $40.00 |
The gap, reconciled to the penny. The 1.99 percent quote predicted a bill of $995.00, because 1.99% of $50,000.00 is $995.00 and the quote named no other fees. The actual bill was $1,450.00. The gap is $455.00, and every dollar of it is accounted for below.
| Component | Amount | Percentage points of volume | Why the quote missed it |
|---|---|---|---|
| Cost the quote did cover (1.99% of volume) | $995.00 | 1.99 | This is the headline rate doing exactly what it promised |
| Percentage-side cost above the quote | $200.00 | 0.40 | Actual percentage cost was 2.39% of volume, not 1.99%, once interchange, assessments, and markup were combined |
| Per-transaction markup | $150.00 | 0.30 | The quote named no per-item amount, and per-item fees hit smaller tickets hardest |
| Fixed monthly fees | $75.00 | 0.15 | Service, gateway, PCI program, and wireless fees bill the same regardless of volume |
| Activity-based fees | $30.00 | 0.06 | Batch and dispute fees are triggered by events, so no quoted rate can predict them |
| Effective rate | $1,450.00 | 2.90 | 1.99 + 0.40 + 0.30 + 0.15 + 0.06 = 2.90 |
The quote was not arithmetically false. It was answering a narrower question than the one the merchant was asking.
Why Headline Rates Mislead
A headline rate is a price for one slice of your activity. Your bill is the whole thing. Five mechanisms create almost all of the distance between them.
Qualified, mid-qualified, and non-qualified tiers
- The advertised rate is the qualified rate: On tiered pricing, the number in the advertisement is the price for the cheapest bucket, and it applies only to volume that lands there.
- Rewards and commercial cards commonly land higher: Consumer rewards, business, corporate, and purchasing cards typically sort into the mid-qualified or non-qualified buckets, which are priced well above the headline.
- The bucket definitions are the provider’s: Which interchange categories map to which tier is a definition inside the pricing program, so the same card can qualify differently under two providers.
- Your tier mix is measurable: The statement usually reports volume by tier, so you can see the share of your sales that never touched the advertised rate.
Downgrades
- A downgrade is a transaction that misses its cheapest category: The sale still settles, but it settles into a more expensive interchange category than it could have.
- Common triggers are procedural: Manually keyed sales without address verification, missing data on commercial cards, and batches settled outside the expected window are frequent causes.
- Your quoted rate never changes: Downgrades raise your effective rate without touching any number in your agreement, which is exactly why the headline stays believable.
Monthly fixed fees spread across your volume
- Fixed fees convert into a percentage only after the fact: A $75.00 fixed monthly stack is 0.15% of $50,000.00 of volume and 0.30% of $25,000.00 of volume, using the illustrative figures above.
- They are invisible in every rate comparison: No percentage quote can express a flat dollar amount, so fixed fees are structurally absent from headline-rate shopping.
- Low-volume merchants feel them most: The smaller your monthly volume, the larger the share of your effective rate that comes from fees having nothing to do with your sales.
Seasonal volume swings
- The same pricing produces a different effective rate every month: Nothing in the agreement changes, but the denominator does.
- Slow months look more expensive: In the illustrative example below, cutting volume in half raises the effective rate from 2.90% to 3.01% with identical pricing.
- Compare like months when you shop: Judging your current provider on a slow month and a prospective one on a projected busy month is not a comparison.
| Scenario | Volume | Transactions | Average ticket | Total fees | Effective rate | Cost per transaction |
|---|---|---|---|---|---|---|
| Baseline month | $50,000.00 | 1,250 | $40.00 | $1,450.00 | 2.90% | $1.16 |
| Slow month, same ticket, no disputes | $25,000.00 | 625 | $40.00 | $752.50 | 3.01% | $1.204 |
| Same volume, half the ticket size | $50,000.00 | 2,500 | $20.00 | $1,600.00 | 3.20% | $0.64 |
Read the third row carefully. Cost per transaction fell from $1.16 to $0.64 while the effective rate rose from 2.90% to 3.20%. A provider who reports only the falling number is telling you something true and useless.
Average ticket shifts
- Per-item fees are a percentage in disguise: A $0.12 per-transaction fee is 0.30% of a $40.00 sale and 0.60% of a $20.00 sale, using the illustrative figures above.
- Interchange also carries a per-item component: Smaller tickets therefore raise the pass-through side of your cost as well, not only the provider’s markup.
- A promotion can move your effective rate: Anything that changes the size of a typical sale changes your effective rate without anyone repricing anything.
The Three Pricing Models and What Each One Hides
The pricing model does not change the arithmetic. It changes how much of the arithmetic you are allowed to see.
| Pricing model | How it is quoted | What the statement shows | Can you see interchange separately? | How the headline can mislead | Effort to compute effective rate |
|---|---|---|---|---|---|
| Flat-rate (bundled) | One percentage, sometimes with one per-transaction amount, applied to all card sales | A single blended charge, often netted out of each deposit rather than billed monthly | No. Interchange, assessments, and markup are combined into one number by design | The quoted number looks like the whole cost, so any monthly, gateway, or dispute fees land entirely outside it | Low. Fees are easy to total, but you cannot tell how much of them is markup |
| Interchange-plus (cost-plus) | Interchange and assessments at cost, plus a stated percentage and per-item markup | Interchange categories listed by name with a subtotal, then the markup shown as its own line | Yes. This is the only common model that itemizes pass-through cost separately | The quoted markup is genuinely small, which can make the total sound smaller than it is once interchange and fixed fees are added | Moderate. More lines to total, but every component is visible and attributable |
| Tiered (qualified, mid-qualified, non-qualified) | A headline qualified rate, with the higher tiers disclosed in smaller print or not at all | Volume and fees grouped by tier, with no interchange detail behind the tiers | No. Interchange and markup are blended inside each tier | The advertised rate applies only to the qualified bucket, and how much of your volume lands there is outside your control | Moderate. The effective rate is easy to compute but impossible to decompose from the statement alone |
Subscription or membership pricing, where a flat monthly amount replaces the percentage markup, is a variant of interchange-plus: interchange still passes through, and the membership fee behaves exactly like the fixed monthly fees described above.
| Pricing model | Costs commonly outside the quoted number | The question that exposes them |
|---|---|---|
| Flat-rate | Monthly platform or software fees, hardware costs, dispute fees, and any fee for faster funding | What will show up on my bank statement in a month where I run zero sales? |
| Interchange-plus | Fixed monthly items, gateway fees, PCI program fees, batch fees, and equipment or wireless charges | List every line that would bill even if my volume were zero, in dollars. |
| Tiered | The mid-qualified and non-qualified tiers themselves, plus the fixed and activity fees | What share of my volume qualified at the advertised rate last month? |
Calculate Your Own Effective Rate
Enter three numbers from a single monthly statement.
- Total volume: The total dollar amount of card sales settled for the month.
- Total fees: Every dollar the processor took that month, including amounts netted from deposits and amounts debited from your bank.
- Transaction count: The number of settled sales for the month.
The calculator returns your effective rate, your cost per transaction, and your average ticket. It does not estimate savings, quote a rate, or compare providers, because none of those can be computed from three numbers.
Effective rate calculator
This calculator runs in your browser. Nothing you enter is sent to us or stored.
Total dollar amount of card sales settled this month
Every fee charged, including fees netted from deposits
Count of settled sales, not batches
What Your Effective Rate Does Not Tell You
- It is not a verdict on your provider: A high effective rate can be driven entirely by your own card mix and average ticket, both of which follow you to any provider.
- It is not comparable across different months: Compare the same month year over year, or run three consecutive months, before drawing a conclusion.
- It is not the same as your markup: Two merchants with identical markup can post effective rates far apart if one accepts mostly rewards cards and the other mostly debit.
- It does not separate fixable from unavoidable: Interchange is not negotiable by any provider, so the useful question is how much of your effective rate sits above it.
If your effective rate is higher than you expected, the next step is finding out which of those categories the excess lives in. Some of it is card mix. Some of it is procedural, such as keyed transactions that could be avoided. Some of it is priced.
For merchants whose goal is to offset card acceptance cost rather than shave the markup, dual pricing and what surcharging is explain how those programs change the arithmetic, and what the rules require.
Frequently Asked Questions
What is an effective rate in credit card processing?
An effective rate is your total monthly processing fees divided by your total monthly card volume, multiplied by 100. It includes every fee: interchange, card-brand assessments, provider markup, per-transaction fees, monthly fixed fees, and activity fees such as batch or dispute charges. It is the only figure that describes what accepting cards actually costs you.
How do I calculate my effective rate?
Take one full monthly statement. Find the total dollar volume of card sales settled and the total of all fees charged for that month, including fees netted from deposits and fees debited from your bank account. Divide total fees by total volume, then multiply by 100. Using illustrative figures, $1,450.00 in fees on $50,000.00 of volume is an effective rate of 2.90 percent.
Why is my effective rate higher than the rate I was quoted?
A quoted headline rate usually prices one part of your activity, while your effective rate counts all of it. The common causes are per-transaction fees the quote did not mention, fixed monthly fees that no percentage can express, volume that settled in a non-qualified tier, downgraded transactions, and activity fees such as dispute charges. Each one adds percentage points that never appear in the quote.
What is a good effective rate for a small business?
There is no single correct number, because effective rate depends on factors outside any provider’s control. Card mix matters, since rewards and commercial cards carry higher interchange than regulated debit. Average ticket matters, since per-item fees are a larger share of a small sale. Card-present versus card-not-present matters. Compare your own effective rate across months and against your own fee detail, rather than against a figure from an advertisement.
Which pricing model shows the true effective rate most clearly?
Interchange-plus is the only common model that itemizes pass-through interchange separately from the provider’s markup, so it lets you decompose your effective rate rather than just calculate it. Flat-rate and tiered pricing both blend interchange into a single number, which means you can still compute your effective rate from either one, but you cannot tell how much of it is markup.
Does a low cost per transaction mean I have a good rate?
Not necessarily. Cost per transaction and effective rate can move in opposite directions. Using illustrative figures, a merchant whose average ticket falls from $40.00 to $20.00 at the same monthly volume can see cost per transaction fall from $1.16 to $0.64 while the effective rate rises from 2.90 percent to 3.20 percent. Always calculate both.
Why did my effective rate go up when nothing about my pricing changed?
Effective rate is a ratio, so it moves when either side of it moves. A slower month spreads the same fixed monthly fees across less volume. A smaller average ticket raises the share of each sale consumed by per-item fees. More rewards or commercial cards in your mix raises interchange. A single dispute fee or an annual fee landing in one cycle also lifts that month.
Related guides
- How to Read a Merchant Services Statement
- Merchant Statement Fee Dictionary: What Every Line Item Means
- Why Did My Credit Card Processing Fees Go Up?
This article is general information for business owners, not legal, tax, or accounting advice. Card brand rules, interchange schedules, and processor agreements change; confirm specifics against your own statement and your own signed agreement.